Awareness

Offer Ends In:
05
Days
:
00
Hours
:
00
Minutes
:
00
Seconds
Worth knowing

Nobody plans to overpay.
Most people just never see the alternative.

Here's what actually decides how much your home loan costs you and why most people never get the full picture.

Your bank can only sell you what your bank has

No branch is going to walk you to a better rate down the street. That's not dishonesty, it's just not their job.

The advertised rate is rarely the real cost

Processing fees, insurance add-ons, and rate resets sit quietly outside that headline number and they add up.

Two banks, same salary slip, two different offers

Eligibility isn't one formula each lender weighs your income, credit, and profile differently.

A 0.25% difference can mean ₹30–50 lakh

Stretched over 20 years, that's not a rounding error that's the difference of a second home.

Not every "advisor" is actually on your side

Some recommendations follow the biggest commission, not the biggest saving for you.

This is exactly the gap an independent advisor closes.

Awareness
Awareness
```
Helping You Get
Better Rates
0
Cr+

Worth of Home Loan Processed

0
+

Banks & NBFCs Compared

0
★

Google Ratings

0
+

Families Helped

Andhra Pradesh • Telangana • NRIs
No sugar-coating

Who Is Really Working For You

Compare
Lendly
Bank
Loan Options
✔ Compares multiple banks
✕ Only its own loan
Advice
✔ Advises what is best for you
✕ Target-Oriented Selling
Recommendations
✔ Independent recommendations
✕ Bank specific only
Negotiation
✔ Helps negotiate better terms
✕ Limited negotiation
Interest Rate
✔ Finds the lowest available rate
✕ Offers only its own rate
Support
✔ Supports throughout the process and after
✕ Focus on approval only
One Bank Gives You One Offer. Lendly Gives You Multiple Options.
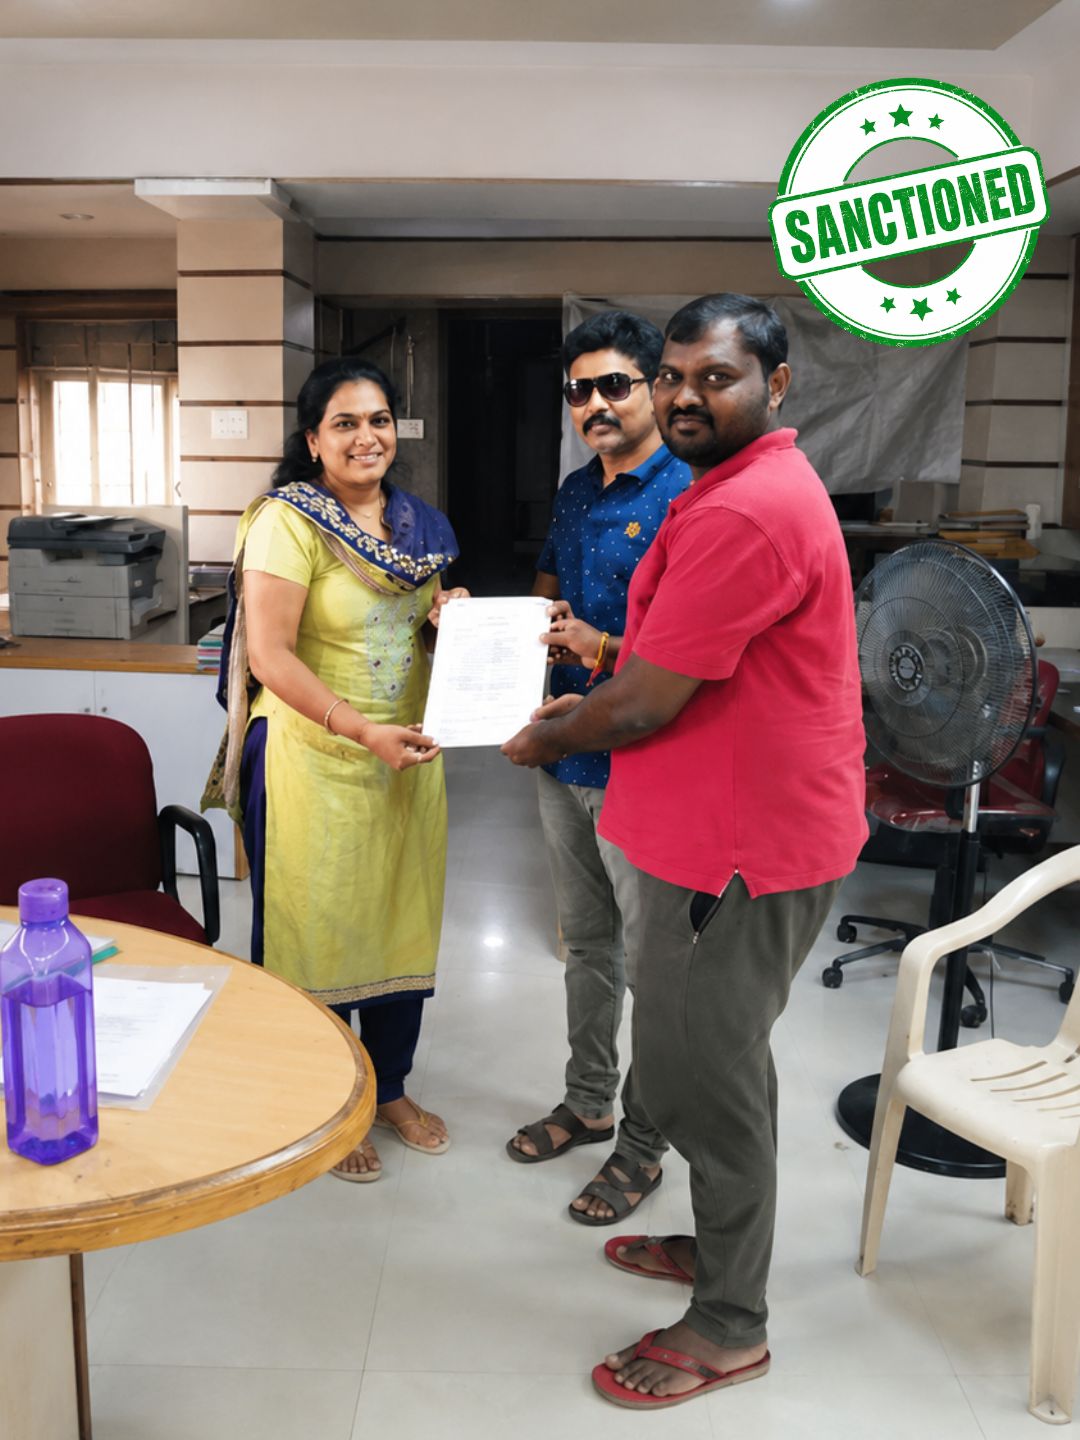
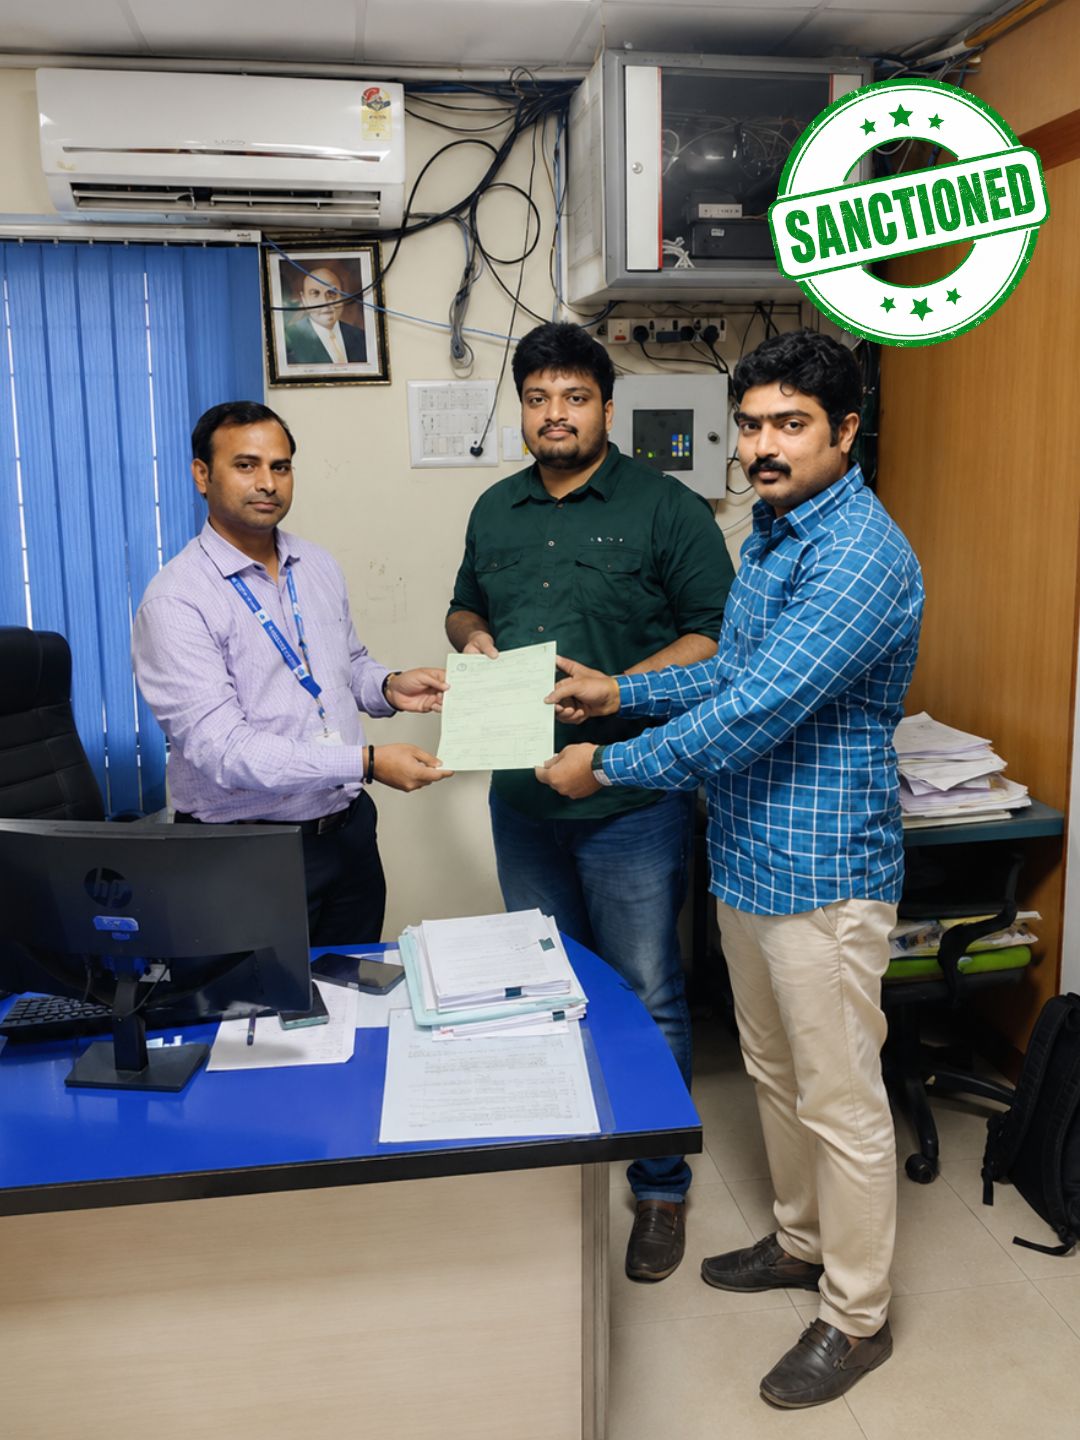
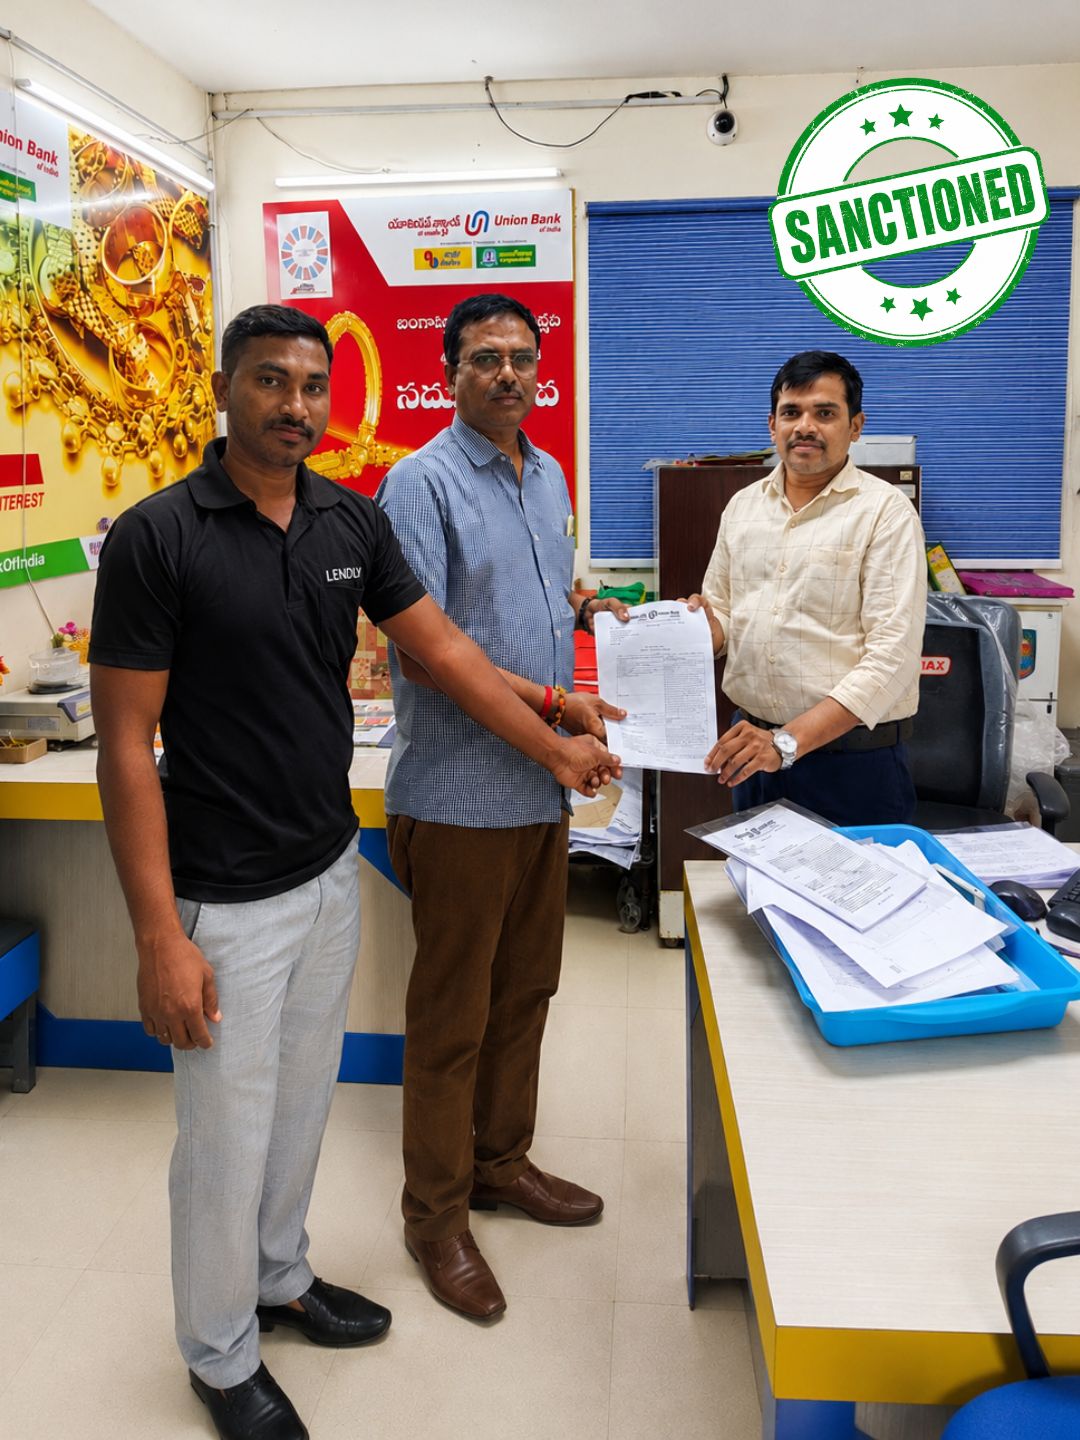
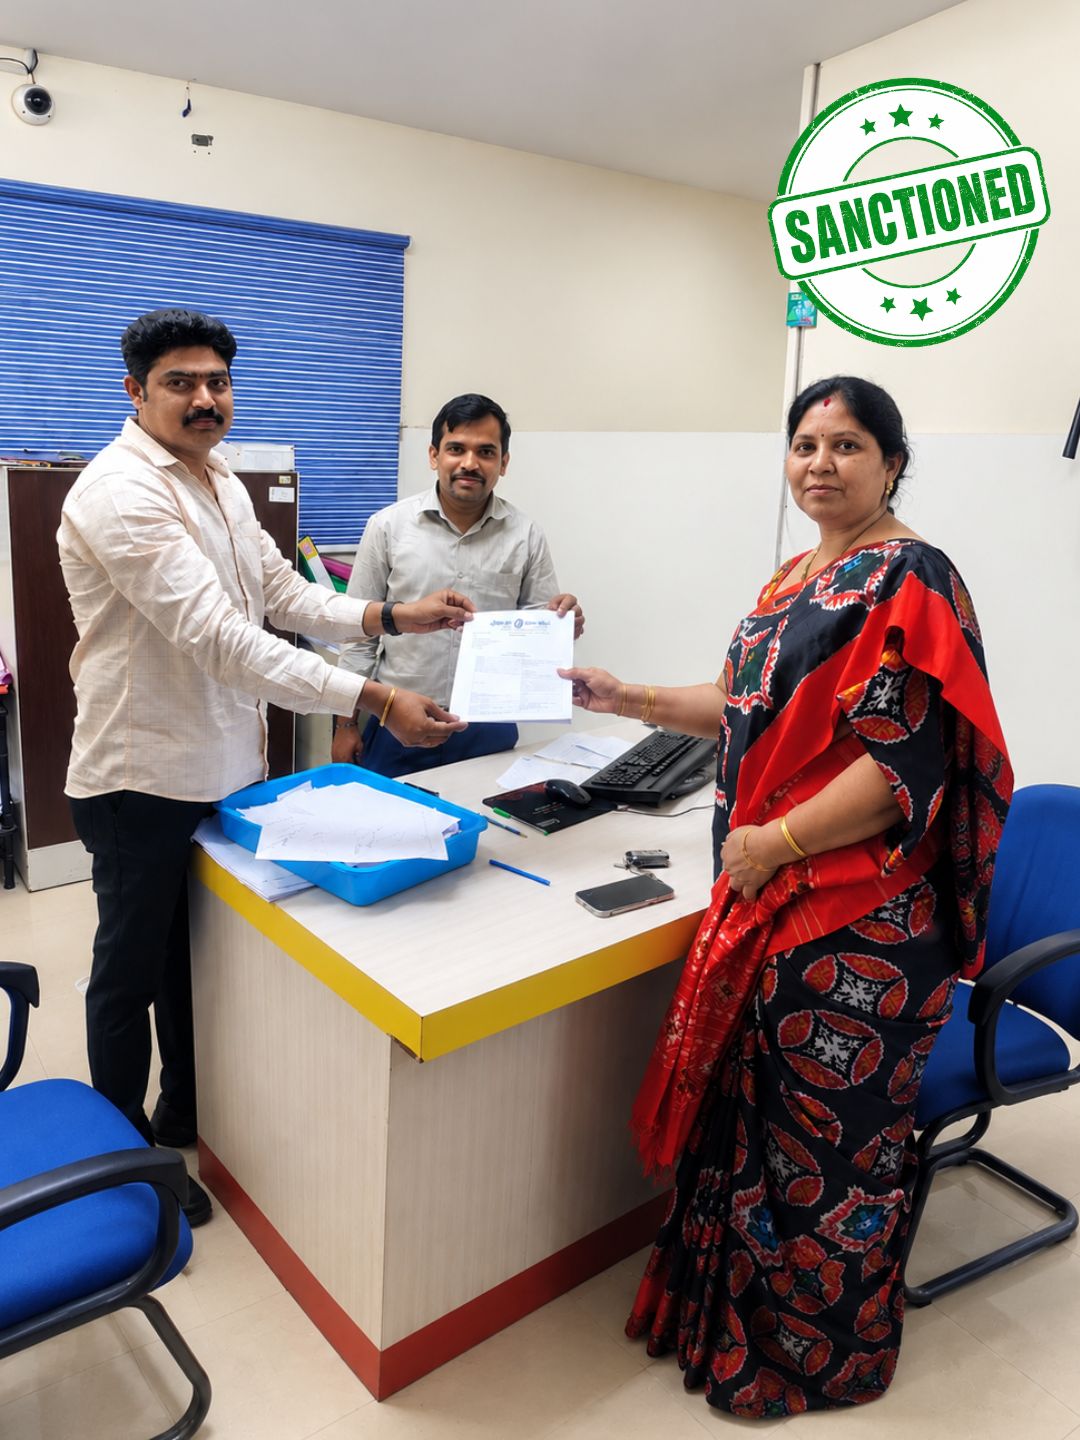
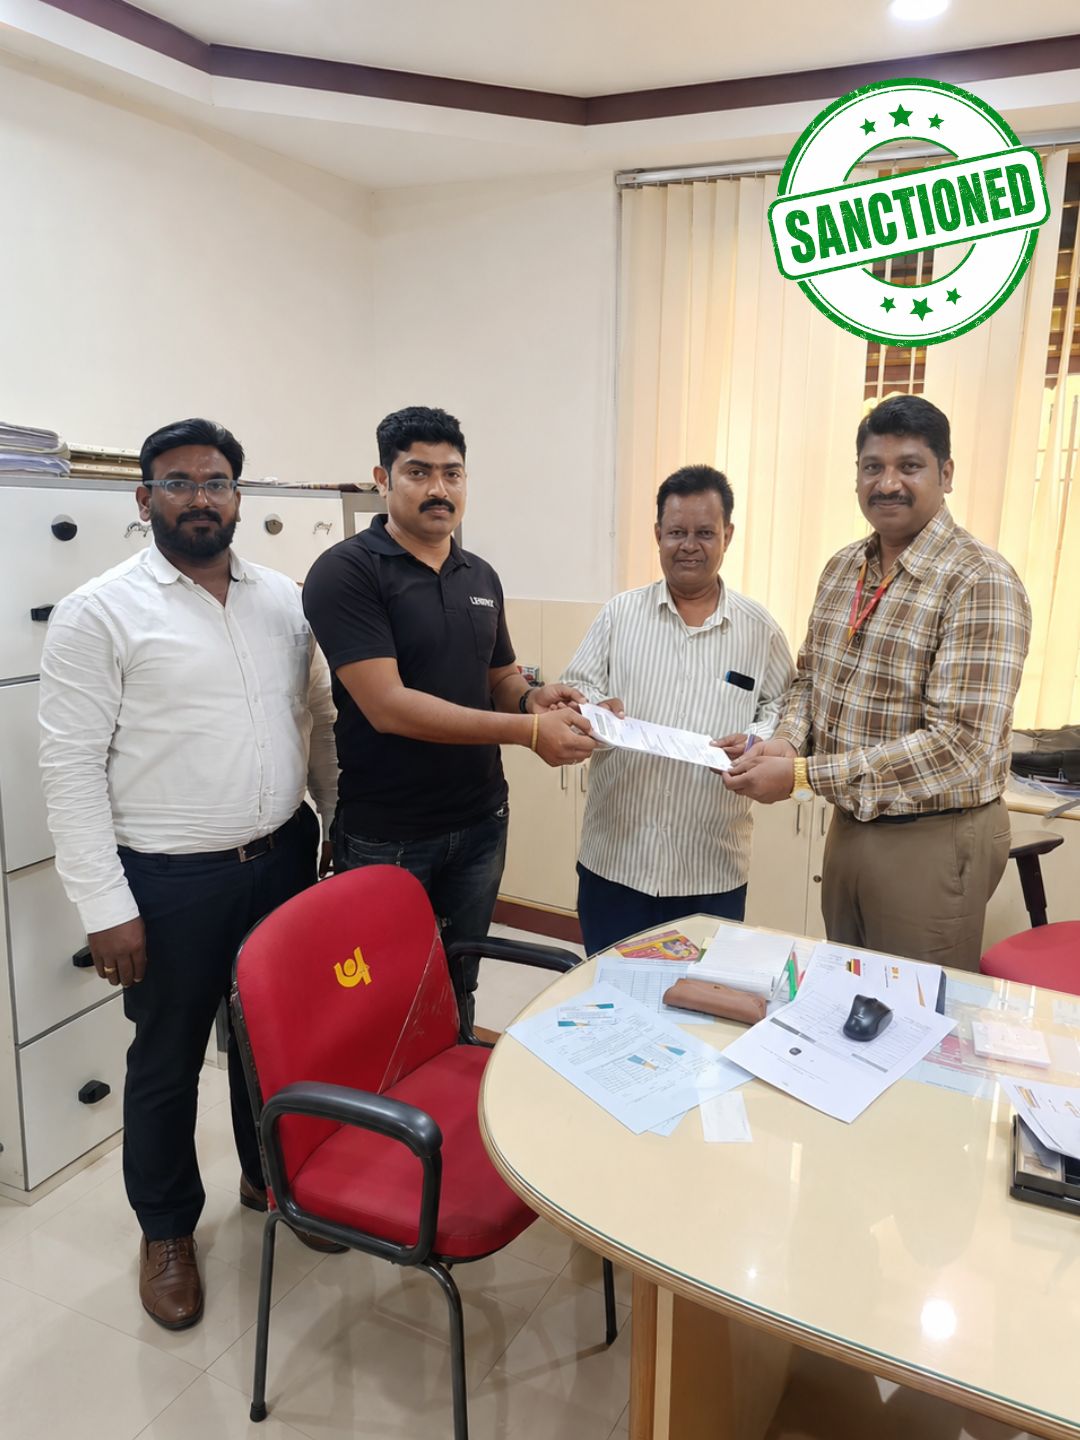
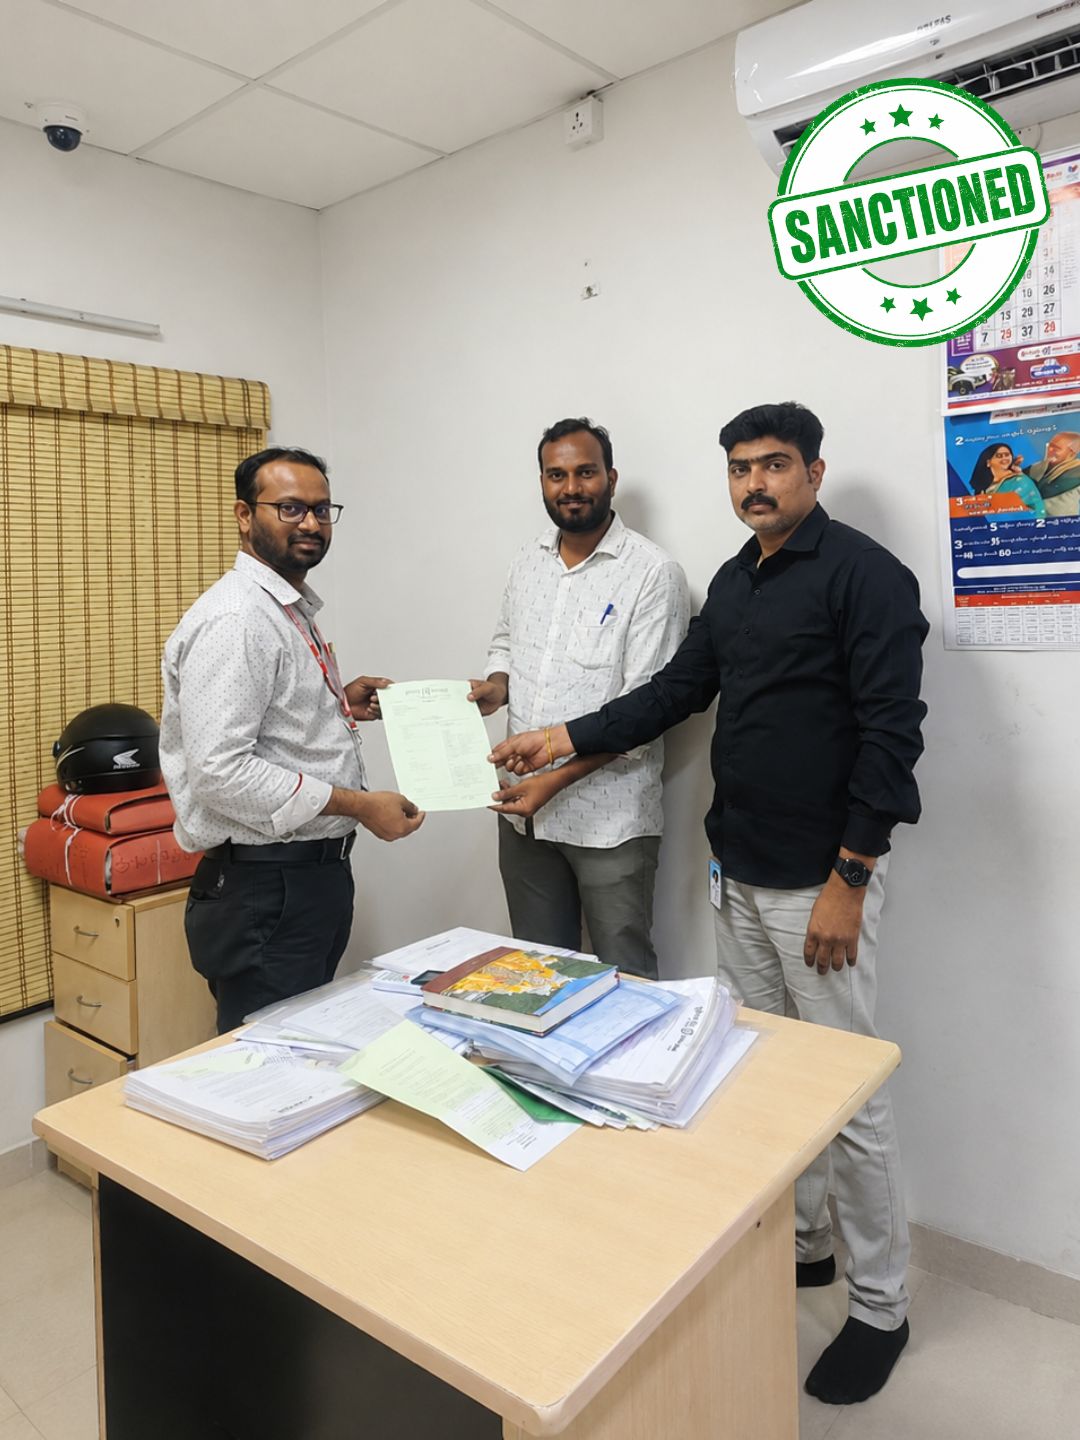
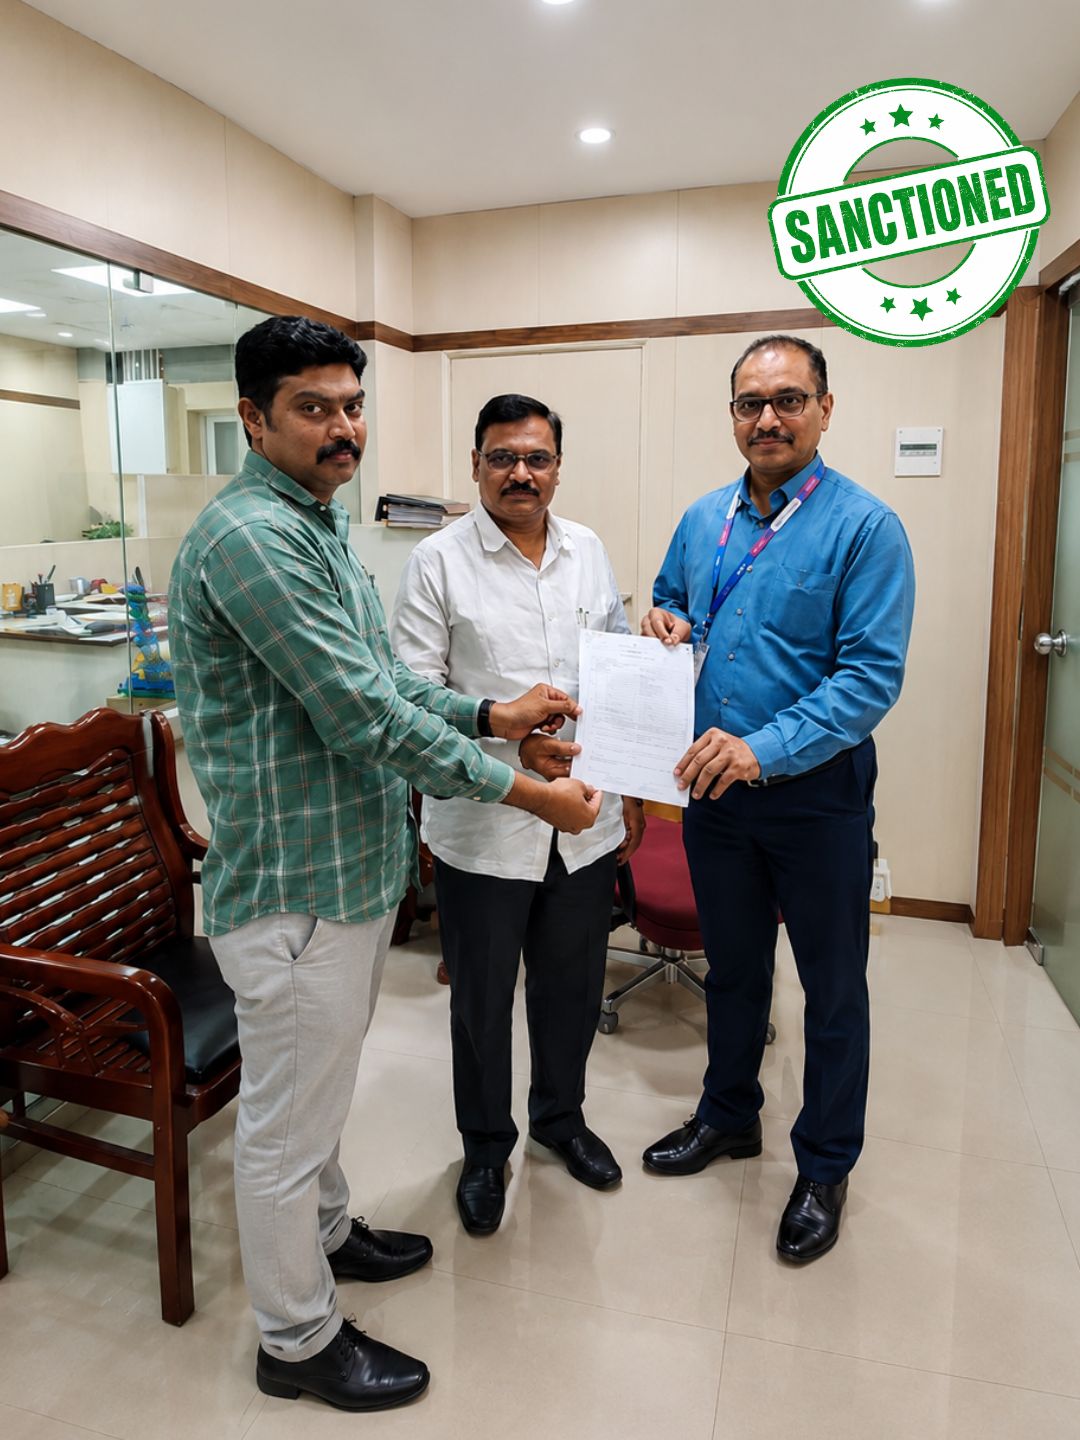
Verified Sanctions

Recent Sanctions. Real People. Real Loans.

Glimpses of home loans we recently helped our clients get.
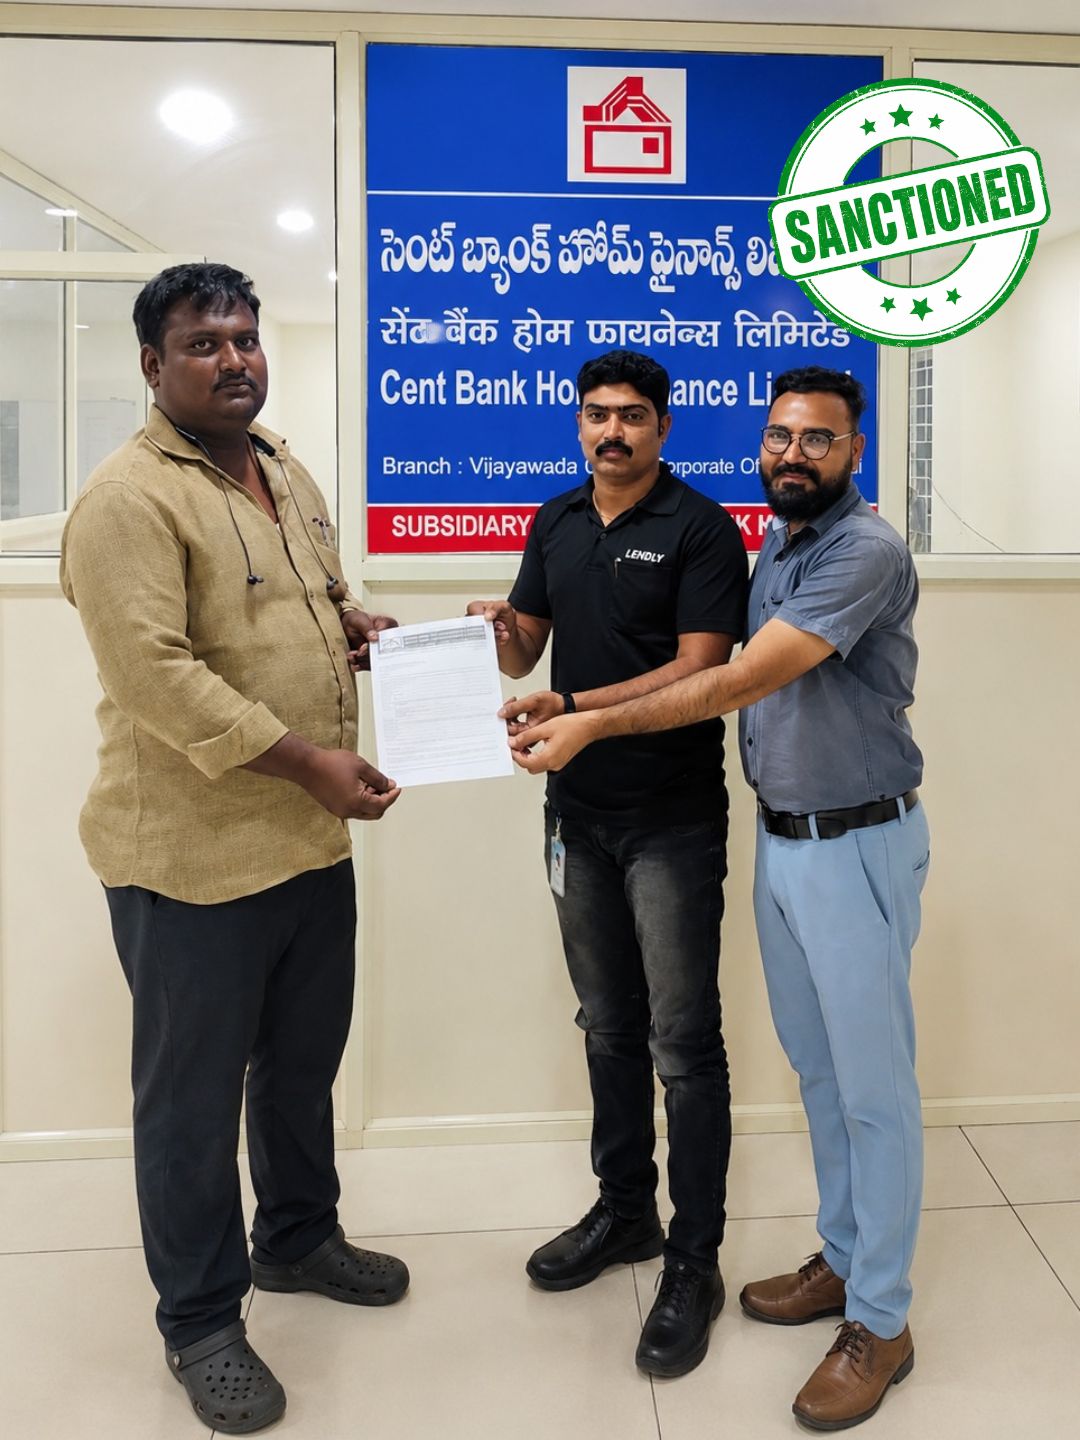
HDFC Bank Home Loan Sanction
Cent Bank Housing Finance
Home Loan
ICICI Bank Home Loan Sanction
ICICI Bank
Home Loan
SBI Home Loan Sanction
SBI
Home Loan
Axis Bank Home Loan Sanction
Axis Bank
Home Loan
Kotak Bank Home Loan Sanction
Kotak Bank
Home Loan
IndusInd Bank Home Loan Sanction
IndusInd Bank
Home Loan
NRI Home Loan Sanction
NRI Home Loan
Sanction
Balance Transfer Sanction
Balance Transfer
Sanction
Bank of Baroda Home Loan Sanction
Bank of Baroda
Home Loan
IOB Home Loan Sanction
IOB
Home Loan

Your Home Loan Journey

Processing timelines and steps differ between nationalised and private banks. Both typically take 7–14 working days.

⏱ Processing time: 7–14 working days
01
By Lendly

Document Collection

KYC documents, financial records, and property documents collected as per Lendly's checklist.

02
By Lendly

Initial Scrutiny

KYC verification, CIBIL score check, and loan eligibility assessment carried out by Lendly.

03
By Bank

Legal & Valuation Initiation

Initiated if the project is not pre-approved. Legal verification and property valuation ordered by the bank.

04
By Lendly

File Login

Approved file submitted (logged in) with the bank for formal processing.

05
By Bank

Field Verification

Bank officials conduct KYC, office, and property inspection visits. Lendly follows up for sanction.

06
Buyer Required

Documentation & Sanction Letter

Buyer visits the bank personally to sign and execute loan agreements. Sanction Letter issued specifying ROI, tenure, and loan amount.

07
By Lendly

Disbursement

A Demand Draft (DD) is issued in the builder's name and handed over. Lendly follows up throughout.

⏱ Processing time: 7–14 working days
01
By Lendly

Document Collection

KYC & financial documents collected digitally. Property documents collected physically. As per Lendly's checklist.

02
By Lendly

Initial Scrutiny

KYC verification, CIBIL check, and eligibility assessment completed by Lendly.

03
Buyer Action

Online Document Upload

Customer uploads all documents via a secure link shared by Lendly or the banker.

04
By Bank

Field Investigation

Bank verifies office, residence, and property through a field visit.

05
Sanction Follow-up & Initial Letter

Sanction Follow-up & Initial Letter

Lendly coordinates with the banker. Customer receives an initial sanction letter showing indicative ROI, tenure, and terms & conditions.

06
Simultaneous

Docket Process (Legal + Valuation)

Legal verification and property valuation happen simultaneously with the sanction process. Applicable for Resale, Construction, LAP, Repairs & Renovation, and Top-Up cases. Not applicable for approved projects (first purchase).

07
By Bank

Final Sanction Letter

Issued after all docket checks are cleared — confirms exact ROI, tenure, and terms & conditions.

This is exactly the gap an independent advisor closes.

Case Studies — Lendly Independent Loan Advisory
Real Client Stories

Where smart advisory
changed the outcome

Five real cases. Five different challenges. One consistent result — the right loan, at the right terms, without unnecessary rejections.

5
Case Studies
₹5.2Cr+
Loans Cleared
10 Days
Fastest Sanction
0
Unnecessary Rejections

Tap any case to read the full story

Each case is a lesson in why the right advisory partner matters more than just the loan amount.

01
When Good Income Isn't Enough — Beating the Bank's Valuation Cap
Software Professional ₹1.3 Cr Construction Loan Sanctioned in 10 Days
Client
Mr. Vinod, Senior Software Professional
Income
₹2.65 L / Month
Loan Needed
₹1.3 Crore (Construction)
Outcome
Full ₹1.3 Cr sanctioned
😟
HDFC Cap at ₹1 Cr
😟
BOB also capped at ₹1 Cr
💡
Lendly analyses LTV angle
🏦
Pitched to IOB higher officials
✅
₹1.3 Cr sanctioned in 10 days
The Problem
1
HDFC: Income-based eligibility confirmed ₹1.3 Cr — but "Technical Sanction" capped it at ₹1 Cr using their average cost-per-sq-ft for construction.
2
Bank of Baroda: Advised closing a ₹10L car loan to improve eligibility. Client paid off the loan — bank still capped at ₹1 Cr for the same reason.
!
Total loss before approaching Lendly: ₹32,000 in non-refundable fees and 20+ days wasted.
Lendly's Strategy
→
Identified that the issue was valuation methodology, not repayment capacity.
→
Land value alone: ₹2 Crore. Total project value: ₹3+ Crore. Loan of ₹1.3 Cr = only 44% LTV.
→
Bypassed automated bank caps by presenting directly to Indian Overseas Bank higher officials.
→
Argued that premium construction specifications justify higher cost-per-sq-ft and proved the bank's risk was exceptionally low.
₹1.3 Crore fully sanctioned
Approved in just 10 days
Proved car loan closure was unnecessary
💡The lesson: Bank software uses average construction costs — not your actual specifications. A strong LTV ratio and the right escalation path can unlock what algorithms block.
02
The Hidden Legal Trap in a Balance Transfer — 6 Families, One Hidden Risk
Group Case — 6 Homeowners Balance Transfer All 6 Approved at Lower Rates
Clients
6 Residents, Group Housing Project
Stuck At
High-rate NBFC loans
Legal Issue
4 of 7 heirs had not signed the sale deed
Outcome
All 6 transferred to nationalized bank
🏠
Stuck in NBFC at high rates
⚠️
Legal defect discovered
💡
Indemnity solution
📋
Deviation proposal
✅
All 6 approved
The Hidden Legal Defect
1
Original owner passed away in 2013. Wife and 2 sons declared themselves "sole legal heirs" and sold to a developer.
2
Family Member Certificate revealed 7 legal heirs — wife, 2 sons, and 4 daughters. None of the daughters signed the sale deed.
!
Title was legally imperfect. Most nationalised banks would have rejected immediately.
Lendly's Strategy
→
Standard rectification risked triggering a family dispute. Lendly found a better path.
→
Leveraged clients' CIBIL scores above 800 and strong salaries as the primary risk mitigation argument.
→
Facilitated a personal indemnity affidavit where borrowers took responsibility for the title.
→
Presented a Deviation Proposal directly to higher authorities.
All 6 loans cleared and disbursed
Moved from high NBFC rates to nationalized bank rates
No family legal dispute triggered
⚠️Important warning: If an NBFC or local builder approves a project, it does not mean the legal title is clean. NBFCs often have relaxed legal checks.
03
How ₹112 and a Secret Job Change Almost Killed a ₹70 Lakh Deal
Sales Executive ₹70 L Home Loan Eventually Approved
Client
Sales Executive, ₹70K–90K/month
Loan
₹70 Lakhs for ₹1.2 Cr house
Root Cause
₹112 overdue on Dhani app loan
Consequence
Heavy interest penalty paid to seller
📝
File submitted
🚫
₹112 overdue rejection
🏃
Client resigns
⏳
Agreement expires
✅
Eventually approved
What Went Wrong
1
The ₹112 default: An old Dhani app loan had an overdue balance of ₹112. Bank's digital system flagged it instantly.
2
The secret resignation: Client resigned without informing Lendly. Bank FI could have caused rejection for Negative FI.
3
New job documentation gap: New offer letter had no Salary Annexure, so the bank had to wait for first payslip.
!
Result: 45-day Sale Agreement expired. Seller charged 2% per month interest on ₹70 Lakhs.
Three Rules to Remember
1
Never hide a small default. A ₹100 overdue can stop a ₹1 Crore loan.
2
Tell your consultant if you plan to change jobs. Applications can be timed or documented better.
3
Fintech/app loans are fully tracked. Obtain NOC for every loan, no matter how small.
💡The lesson: At Lendly, we clear the path — but transparency from the client saves time, reputation, and money.
04
The "Approved Project" Myth — How Missing Old Documents Killed a Deal in 10 Days
Air India Pilot Mortgage Loan (LAP) Deadline Missed Due to Docs
Client
Air India Pilot, ₹2.58L/Month
Loan Type
Mortgage (LAP) — Agriculture Land
Rate Locked
8.5% via Axis Bank
Outcome
Deal dropped due to expired deadline
⏰
10-day deadline
💰
8.5% rate locked
🔍
Legal scrutiny issue
📁
Old docs unavailable
❌
Deadline expired
The Problem
1
Property was in a known highway project, but the original builder went bankrupt and a new developer took over.
2
Client assumed "bank-approved project" meant instant legal clearance. This is incorrect for LAP, resale, or balance transfer.
3
Andhra Pradesh's CARD system only shows documents digitally from year 2000 onwards. Older documents need manual CC requests.
!
Neither the client nor builder had old link documents. The 10-day window expired.
The Approved Project Reality Check
!
A bank's APF only simplifies the process for the first-time buyer purchasing directly from the builder.
!
For Resale, Balance Transfer, or Mortgage Loan, the bank demands the full document chain again.
Lendly's Be Loan-Ready Protocol
→
The 13 vs 30 Rule: Private banks typically need 13-year chain. Nationalised banks need 30 years.
→
Build a Digital Vault: Keep scans of all link documents, allotment letters, and sale deeds.
→
Obtain your own Certified Copies from the SRO once and keep them safely.
💡The lesson: "Approved" does not mean "ready." Maintain your complete document chain to protect future opportunities.
05
₹88K Monthly EMIs and an 18-Year Legal Chain — How the Right Bank Made It Possible
Software Professional ₹1.2 Cr Home Loan 15-Year Tenure Secured
Client
Raghuram, Software Professional
Existing EMIs
₹88,000/month
Legal Chain
Only 18 years
Outcome
₹1.2 Cr at 15-year tenure
🚫
FOIR too high
🚫
18-yr chain rejected
💡
Private bank pivot
📋
Closing loans excluded
✅
₹1.2 Cr approved
Why PSU Banks Said No
1
Legal chain gap: Property documents showed only 18 years. PSU banks require a 30-year Mother Deed search report.
2
FOIR too high: Existing car and personal loan EMIs totalled ₹88,000/month.
The Private Bank Advantage
→
The 6-Month Closing Rule: HDFC, Axis, and ICICI may exclude loans closing within 6 months from FOIR.
→
By excluding ₹88,000 from obligations, his effective repayment capacity increased.
→
Private banks generally accept a 13 to 15-year legal chain for sanctioned projects with marketable title.
PSU Banks — Blocked
Requires 30-yr legal chain
All EMIs counted regardless
Rigid FOIR rules
Private Banks — Approved
Accepts 13–15 yr legal chain
Loans closing in 6 months excluded
Nuanced credit policy
₹1.2 Crore loan approved
15-year tenure secured
No unnecessary bank rejections
💡The lesson: Your salary matters. But the right lender matters just as much. Professional consultancy identifies exactly which bank's policy fits your timeline.
Home Loan EMI Calculator
Loan Amount
₹
₹10 L₹2 Cr
Rate of Interest (p.a.)
%
5%20%
Loan Tenure
Yr
1 Yr30 Yr
Monthly EMI
—

Principal amount—
Total interest—
Total amount payable—
Total payable
—
Principal
—
Interest
—
Amortization Details
YearPrincipal (₹)Interest (₹)Balance (₹)
Still wondering?

Frequently Asked Questions

Will my credit score be affected
No. Booking a consultation does not affect your credit score.
How long is the consultation
Typically 20 to 30 minutes depending on your requirements.
Do you work with multiple banks
Yes. We compare 35+ banks and NBFCs to identify suitable options for your profile.
Is Lendly a bank
No. Lendly is an independent home loan advisory firm that helps you compare and choose the right lender.
Can existing home loan borrowers book this consultation
Yes. We also help review existing loans for refinancing, balance transfer, better loan structure and interest savings.
What happens after I book
Your advisor reviews your profile, contacts you at your preferred time and guides you through the next steps.

Your Home Loan Journey

Processing timelines and steps differ between nationalised and private banks. Both typically take 7–14 working days.

⏱ Processing time: 7–14 working days
01
By Lendly

Document Collection

KYC documents, financial records, and property documents collected as per Lendly's checklist.

02
By Lendly

Initial Scrutiny

KYC verification, CIBIL score check, and loan eligibility assessment carried out by Lendly.

03
By Bank

Legal & Valuation Initiation

Initiated if the project is not pre-approved. Legal verification and property valuation ordered by the bank.

04
By Lendly

File Login

Approved file submitted (logged in) with the bank for formal processing.

05
By Bank

Field Verification

Bank officials conduct KYC, office, and property inspection visits. Lendly follows up for sanction.

06
Buyer Required

Documentation & Sanction Letter

Buyer visits the bank personally to sign and execute loan agreements. Sanction Letter issued specifying ROI, tenure, and loan amount.

07
By Lendly

Disbursement

A Demand Draft (DD) is issued in the builder's name and handed over. Lendly follows up throughout.

⏱ Processing time: 7–14 working days
01
By Lendly

Document Collection

KYC & financial documents collected digitally. Property documents collected physically. As per Lendly's checklist.

02
By Lendly

Initial Scrutiny

KYC verification, CIBIL check, and eligibility assessment completed by Lendly.

03
Buyer Action

Online Document Upload

Customer uploads all documents via a secure link shared by Lendly or the banker.

04
By Bank

Field Investigation

Bank verifies office, residence, and property through a field visit.

05
Sanction Follow-up & Initial Letter

Sanction Follow-up & Initial Letter

Lendly coordinates with the banker. Customer receives an initial sanction letter showing indicative ROI, tenure, and terms & conditions.

06
Simultaneous

Docket Process (Legal + Valuation)

Legal verification and property valuation happen simultaneously with the sanction process. Applicable for Resale, Construction, LAP, Repairs & Renovation, and Top-Up cases. Not applicable for approved projects (first purchase).

07
By Bank

Final Sanction Letter

Issued after all docket checks are cleared — confirms exact ROI, tenure, and terms & conditions.

This is exactly the gap an independent advisor closes.

Free ₹4999
Limited Time Offer
Only 5 Slots Left Review My Loan For Free
Awareness
```